Free guide · Investing basics
Don't lock ₹3 lakh in one FD. Build a ladder instead.
A complete guide to FD laddering: real numbers, what an emergency costs, and how to set up your own ladder at the bank.
10 pages · Verified Oct 2026 · Free to share
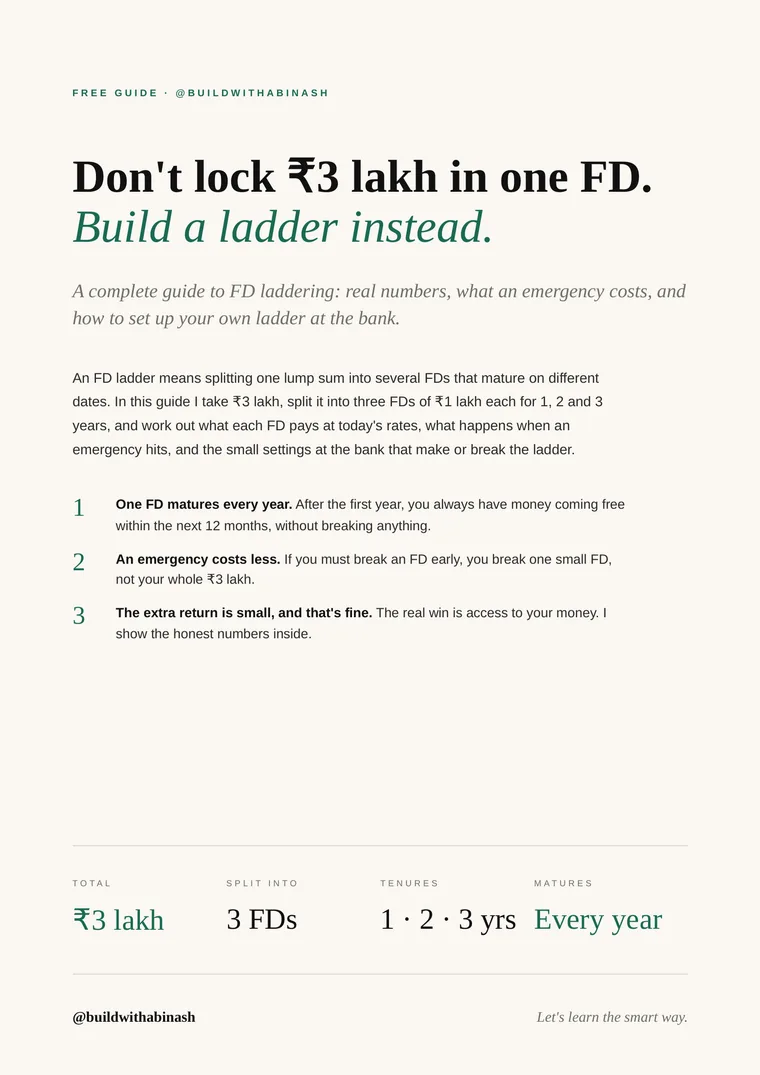
The numbers at a glance
- Total
- ₹3 lakh
- Split into
- 3 FDs
- Tenures
- 1 · 2 · 3 yrs
- Matures
- Every year
Worked out at a large public-sector bank's October 2026 rates: 6.25% for 1 year, 6.40% for 2 years and 6.30% for 3 years, compounded quarterly, before tax.
The one thing to notice
A ladder is not a return trick. Breaking one ₹1 lakh FD in month 8 loses ₹580 of interest; breaking one ₹3 lakh FD loses ₹1,844.
What's inside the PDF
- 1The basic plan. ₹3 lakh, three FDs, one maturity every year.
- 2Three things people get wrong. Returns, safety, and never breaking an FD.
- 3The ladder, year by year. How every rung rolls into a 3-year FD.
- 4Ladder vs one big FD. Normal years, and an emergency in month 8.
- 5Make it fit your life. The five dials: rungs, gaps, size, interest, banks.
- 6Set it up this week. Six steps, and the maturity setting most people miss.
- 7Tax, safety and good habits. TDS, Form 121 and the ₹5 lakh DICGC limit.
- 8The glossary, in plain words. Every term, with a line in Tanglish.
More like this
New guides land on Instagram first.
A short video most days, and the PDF in the comments when enough people ask for it.
Follow @buildwithabinashHow I checked this
- Every total computed in code, not by hand
- Sources listed on the last page of the PDF
- Re-checked on Oct 2026
Disclaimer
Education only, not investment advice, and not a recommendation of any product. I am not a SEBI-registered investment adviser. FD rates, penalties, tax rules and insurance limits change, and differ by bank. The figures are examples on stated assumptions, not promised returns. Check your bank's current terms before acting.