Free guide · Loans and debt
Bank account in minus? That fine may not be legal.
The full RBI rules behind my negative balance video, plus the exact email and the complaint steps to get it fixed.
9 pages · Free to share
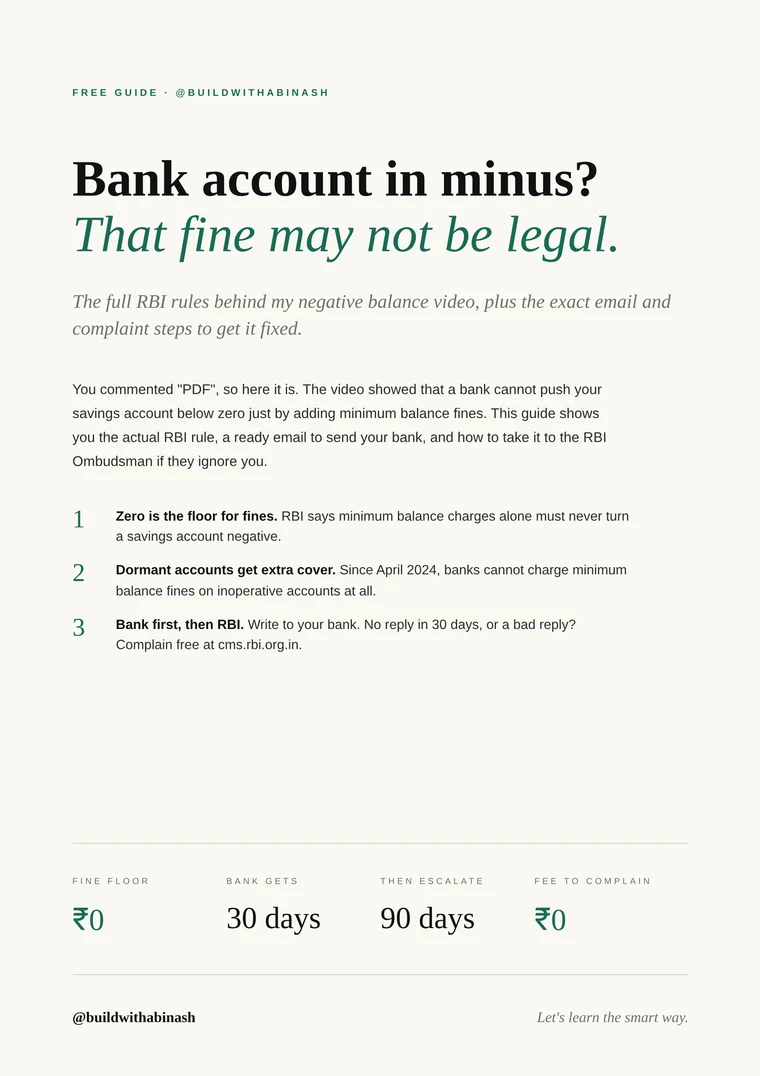
The numbers at a glance
- Fine floor
- ₹0
- Bank gets
- 30 days
- Then escalate
- 90 days
- Fee to complain
- ₹0
Minimum balance charges alone must not take a savings account below zero. The 30 days is how long the bank has to reply, not a deadline to reverse the fine.
The one thing to notice
The rule protects you from minimum balance fines only. If the minus came from something else, a loan EMI or a cheque bounce charge, ask the bank to explain each debit first.
What's inside the PDF
- 1Zero is the floor for fines. The RBI rule, and where it is written.
- 2Dormant accounts get more cover. No minimum balance fine at all since April 2024.
- 3The email to send your bank. Ready to copy, with what to attach.
- 4Bank first, then the Ombudsman. 30 days to reply, then cms.rbi.org.in, free.
- 5What the video got slightly wrong. The 30 days is to respond, not to reverse.
More like this
New guides land on Instagram first.
A short video most days, and the PDF in the comments when enough people ask for it.
Follow @buildwithabinashHow I checked this
- Every total computed in code, not by hand
- Sources listed on the last page of the PDF
- Check date shown on the PDF
Disclaimer
Education only, not investment advice, and not a recommendation of any product. I am not a SEBI-registered investment adviser. It covers minimum balance charges and inoperative accounts; other debits follow different rules. I am not a lawyer either. Check the latest RBI notification before acting.